Tokenisation news, 9 September 2026
The SEC proposes its first transfer agent rules overhaul in 40+ years, South Korea sets a three-phase legal roadmap for tokenised securities, and Janus Henderson's tokenised funds start managing reserves for corporate loyalty programmes worth $300bn a year.
Key takeaways
- The US SEC proposed its first substantial rewrite of transfer agent rules since the late 1970s/early 1980s, explicitly addressing blockchain-based recordkeeping, with a 60-day public comment period once published in the Federal Register.
- South Korea's Financial Services Commission unveiled a three-phase roadmap for tokenised securities, with Phase 1 beginning February 2027 covering privately pooled money market funds and bonds, unlisted trust-structured stocks, and publicly offered fractional investment products.
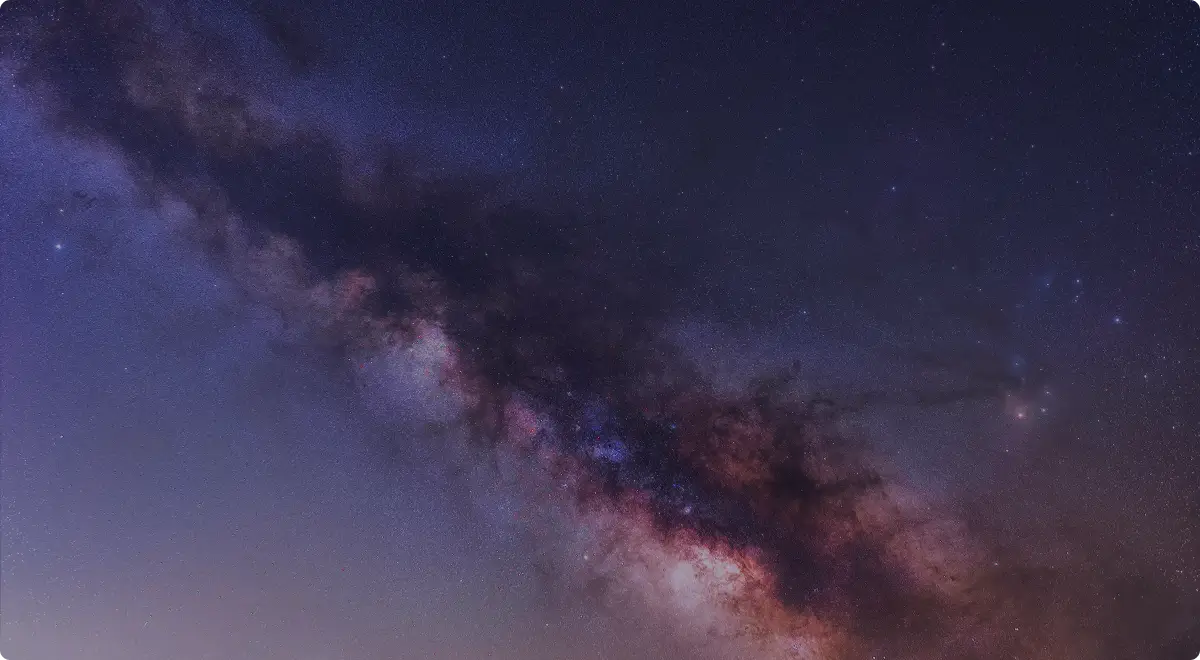
- Janus Henderson, Centrifuge and SmartMedia Technologies partnered to let corporate loyalty programmes hold cash reserves in Janus Henderson's tokenised JTRSY and JAAA money market funds, which together manage $1.5 billion.
- The global loyalty industry issues upwards of $300 billion in points and rewards annually — the addressable backdrop for the Janus Henderson partnership.
US SEC proposes first transfer agent rule overhaul in more than 40 years
The US Securities and Exchange Commission has proposed its first substantial rewrite of the rules governing transfer agents — the firms that keep the official record of who owns a company's shares and process changes in that ownership — since those rules were written in the late 1970s and early 1980s. The proposal explicitly covers how transfer agents can rely on electronic recordkeeping and blockchain-based systems in their work. SEC Chairman Paul Atkins said the changes are meant to bring the rules in line with how transfer agents actually operate today. The proposal will be open for public comment for 60 days once it is published in the Federal Register.
The Investre take: A regulator writing blockchain-based recordkeeping into the rulebook for transfer agents is exactly the kind of legal groundwork Luxembourg's Control Agent regime already provides. The real signal here isn't the SEC's timeline, it's that who legally holds the register on-chain is now a mainstream regulatory question, not a niche one.
South Korea sets a three-phase legal timeline for tokenised stocks, bonds and funds
South Korea's Financial Services Commission has unveiled a three-phase roadmap to give tokenised securities — stocks, bonds and funds represented and transferred using blockchain technology — formal legal status. The first phase begins in February 2027 and covers privately pooled money market funds and bonds for institutional investors, unlisted stocks issued through a trust structure, and publicly offered fractional investment products. The second phase extends tokenisation to all publicly offered securities, and the final phase aims to connect securities settlement with stablecoin-based payments.
The Investre take: Korea just gave itself a legal deadline for tokenised securities while Europe is still negotiating what its own falls under. The lesson for European fund managers watching from the sidelines is that regulatory clarity, once written down with a date attached, moves faster than anyone expects.
Janus Henderson's tokenised funds start managing cash behind corporate loyalty programmes
Asset manager Janus Henderson, tokenisation platform Centrifuge, and loyalty-technology firm SmartMedia Technologies have partnered to let corporate loyalty programmes — such as airline miles or retail points schemes — hold their cash reserves in tokenised money market funds instead of ordinary bank accounts. The reserves sit in Janus Henderson's JTRSY and JAAA funds, which together manage $1.5 billion and record ownership on a blockchain rather than a traditional register. Because the reserve balance is visible in real time, a loyalty programme can check it holds enough money before issuing new points, rather than discovering a shortfall afterwards. The loyalty industry issues upwards of $300 billion worth of points and rewards annually.
The Investre take: A tokenised fund is no longer just a wrapper for institutional cash, it is starting to double as working capital infrastructure for entirely different industries. European fund managers should take note: the more places a tokenised share ends up living, the more the underlying register needs to hold up under uses nobody designed it for.
What this means for European fund managers
European fund managers don't need to wait for their own version of these regulatory moves. Luxembourg's Blockchain IV Law already gives asset managers the legal basis to do this today: an authorised Controlling Agent can maintain a fund's official share register on a distributed ledger, without needing a separate transfer agent or central securities depository. Investre was the first firm authorised for this role in Luxembourg.
Further reading: Investre becomes the first Controlling Agent under Blockchain IV Law, or The Final Block podcast.
Authors